Key Takeaways
- Finding a fee-only financial advisor is important to align financial interests and avoid product sales.
- Fee-only advisors typically charge a percentage of assets under management and some also have a fiduciary duty to act in clients’ best interests.
- Consider attributes like specialization, independence, and service models while searching for an advisor.
- Use targeted web searches, AI resources like Claude, websites like NAPFA, and personal referrals to find fee-only financial planners.
- Evaluate potential advisors based on firm structure, professional designations, services, and personal compatibility. Location-based options may be limiting, especially if you don’t plan on having regular in-person meetings.
Finding the Right Fee-Only Financial Planner
If you’re looking for a fee-only financial advisor or wealth manager, it’s probably because you know fee-only advisors don’t sell products.
Finding the right financial advisor is so important. Here are three ways to find the best fee-only financial advisor to suit your needs, five criteria to keep in mind, and a quick checklist when evaluating advisors. Here’s an explainer on the differences between fee-only and fee-based advisors.
What is a Fee-only Advisor and How Do They Charge?
Fee-only advisors are unique as they are only paid by their clients. Fee-only financial advisors do not receive commissions from selling financial products, such as insurance policies or investment products, or payments from third parties. This compensation structure is designed to reduce conflicts and align interests between the advisor and client.
The term fee-only can be confusing to investors. It’s a common misconception that all firms charge on an hourly basis or or a flat fee. Although some firms use these compensation methods, the majority of fee-only advisors charge a percentage of assets under management (AUM) for their services.
Fee-only financial advisors are often registered investment advisors too, meaning they have a legal duty to act in the client’s best interest. This fiduciary duty is a cornerstone of their practice, providing clients with the confidence that their financial advisor is working solely for them.
Top Considerations in Your Fee-Only Financial Advisor Search
There’s a lot to consider when searching for a fee-only financial planner. When thinking about the criteria that matters most to you, keep these five elements in mind.
Fee-only fiduciary
While many fee-only advisors are also fiduciaries, it isn’t a requirement. Only fiduciary financial advisors are legally bound to act in your best interest at all times. A registered investment advisor is the only type of financial advisory firm required to act as a full-time fiduciary.
Independent firm
Many advisory and investment management firms are subsidiaries of a larger parent corporation or have affiliations with companies that offer other services, like life insurance or investment products. Working with an independent firm can reduce the risk of receiving biased advice.
Specialization and niche financial planning focus
The ability to advise on standard financial planning matters such as retirement planning is table stakes when looking for a fee-only planner. But even comprehensive wealth advisors can have blind spots on certain subjects. Consider any unique factors to your situation and whether those complexities might require the support of a financial advisor who specializes in that niche practice area.
For example, if you have stock options or equity compensation at a company that’s going public, you’ll want to find a fee-only financial advisor who specializes in pre-IPO financial planning. There are financial advisors who focus on working with dentists, teachers and professors, and business owners, and even sudden wealth financial advisors.
Do you really need a fee-only financial advisor near you?
For many investors, the most important factor when trying to find fee-only financial planners is location. In-person meetings may be ideal for some, but technology makes meeting face-to-face easy, regardless of your location.
Consider prioritizing your financial needs and the right overall fit versus just Googling best financial advisor near me. After all, if you move, or if your advisor does, you probably won’t want to start over with a new firm. Fee-only SEC-registered investment advisors can typically support clients regardless of their current state of residence.
Service model
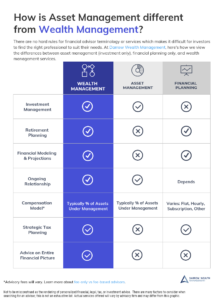
What are you looking for a financial advisor for? Finding the right advisor often comes down to the services they offer. Before starting your search, ask yourself if you want ongoing wealth and asset management, hourly financial planning advice without asset management, or a one-time or project-based engagement without any ongoing relationship or implementation support?
Most advisors don’t offer all three, so determining what service model you want ahead of time can streamline your search. And remember: fee-only means the advisor is paid only by their clients. No commissions, referral fees, or product sales. That doesn’t mean they don’t manage money, though. Many fee-only advisors manage investments and charge a percentage of the assets they oversee.
Finally, also consider whether you want one firm handling financial planning and tax preparation in-house versus an advisor to quarterback efforts with a team approach. Although it might seem best to have one firm filing your taxes and giving you financial advice, with so many tax deadlines throughout the year, it may affect turnaround times if you need something unexpectedly or during tax season.
3 Ways to Find a Fee-only Financial Advisor
Here are three ways to find a fee-only wealth management firm (in no particular order).
1. Targeted Search (Traditional Web Search or AI agent like Claude or ChatGPT)
A Google search for fee-only financial advisor near me returns about 500 million results. So, that’s a lot. Consider adding specific attributes that are important to you to help narrow the list. Getting into specifics can be especially helpful when using AI to help you find a financial advisor.
For example, do you prefer large national firm or small team? Or maybe you need a firm that focuses on working with business owners before a sale, widows, or founders and tech employees with equity.
With a narrow search, Google can be a great starting point to help you find a fee-only financial planner.
2. The National Association of Personal Financial Advisors
The National Association of Personal Financial Advisors (NAPFA) may come up in some of your searches for an advisor. NAPFA members are all fee-only. However, if you’re trying to find a fiduciary investment advisor, you’ll need to do some extra homework to see if the firm is also a registered investment advisor.
NAPFA can be a useful resource for some individuals, particularly investors just starting out or those with more limited financial planning needs, perhaps hourly or one-time plans. The database might be limiting for high net worth investors seeking comprehensive advice and ongoing investment management.
And remember, not all fee-only investment advisors choose to become members of NAPFA. Consider using multiple avenues when looking to find a financial advisor.
3. Ask for Referrals
Asking friends, family, coworkers, an accountant, or personal lawyer for a referral can be one of the most effective ways to find a fee-only financial advisor. But like these other options, it isn’t fool-proof. Many investors aren’t aware of the differences between fee-only and fee-based advisors – even if they’re working with one.
Personal referrals are especially helpful to get a sense of fees and services. Asking around can be a helpful starting point but consider doing your own research on the planner and firm before engaging.
Checklist: Evaluating a Financial Planner
When evaluating a financial planner and advisory firm, there’s a lot to consider. Here are a few factors to consider in your search.
- Firm structure: Aside from fee-only, consider prioritizing firms that are also registered investment advisors as they must follow a fiduciary standard. Independence is important too, as it can also help ensure investment advice is in your best interest.
- Titles: Financial planners go by many names. Titles alone shouldn’t be relied on when evaluating competence, fit, or alignment with your needs. Planners often go by some combination of terms like [financial, retirement, investment, money, wealth] followed by words like advisor, planner, consultant, manager, specialist. Don’t get too hung up here.
- Professional designations: Look for certifications, but don’t inflate the value of a long string of letters after someone’s name. There are so many credentials in the financial services industry, each with their own standards, qualifications, and merits. The CERTIFIED FINANCIAL PLANNER™ professional (also CFP® professional) designation is often considered the gold standard for financial planners. You can also search for a planner on the CFP board website. On the investment side, it’s the CFA®.
- Financial planning services: Confirm alignment with the advice you’re seeking. Are you looking for ongoing wealth management services? Or an advice-only relationship? Consider the level of implementation support you want and the duration of the engagement, too.
- Personality: Finding the right advisor means you need someone who has a personality that aligns with yours and with whom you feel comfortable discussing your financial situation and other sensitive matters.
Finding the Right Long-Term Financial Partner
At the end of the day, if you or your spouse doesn’t feel confident with or heard by an advisor, it’s probably not a good fit. If you don’t see yourself picking up the phone or reaching out with a question or life update, you’re not going to get what you need out of the relationship.
It’s also important not to compromise on the aspects of the relationship that are important to you. We all have a friend or family member who’s ‘got a guy’ at Morgan Stanley. But if you really want to work with a fiduciary fee-only financial advisor, it might not be a good match, despite the recommendation. Liking and trusting an advisor is paramount, but so too is having the official status to back it up.
Darrow Wealth Management is proud to be:
- Fee-only
- Full-time fiduciary advisors
- CERTIFIED FINANCIAL PLANNER™ professionals
- Independent
- Registered investment advisor
Book a consultation with a fee-only advisor today.
FAQ: Finding a Fee-Only Wealth Advisor
A fee-only financial advisor is paid exclusively by their clients, typically as a percentage of assets under management. These advisors don’t earn commissions or sells financial products. Fee-based advisors, by contrast, can collect both client AUM fees and third-party commissions — for example, by selling life insurance, annuities, or mutual funds.
Fee-only advisors can be paid as a percentage of the assets they manage, charge hourly planning fees, retainers, or project-based fees like the development of a financial plan.
The cost of working with a fee-only financial advisor can range considerably. It often depends on the complexity of the client’s situation, scope of the engagement, level of assets managed by the advisor, and if the advisor charges one fee for comprehensive services or uses a pricing menu.
A fee only fiduciary is often a fee-only registered investment advisory firm. This type of firm combines the client-only compensation model of fee-only advisors with the fiduciary duty a registered investment advisor (RIA) has.
Consider specialized planning areas, services, fees, and alignment with your personal and financial profile.
[Last reviewed October 2026]